YNAB

Screenshots
Details
- Rating
- 4.53K reviews
- Version
- 25.37.2
- Developer
- ynab.com
Analysis by Norviv
Most budgeting problems do not begin with complicated arithmetic; they begin when setup asks you to make choices before you know how you want to manage your money. YNAB is built around assigning available money to planned purposes, so the first hurdle is deciding what those purposes should be. I found it more useful to start with the next few weeks of real obligations than to design a perfect category system on day one. Rent, groceries, transport, and bills make a practical first pass; you can refine the details once the routine feels familiar.
The app is a finance tool from ynab.com, and its approach is quite different from a basic expense tracker. Instead of mainly showing where money went after the fact, it asks you to make a plan for what you have available now. That distinction is the reason it can feel clarifying, but it is also why setup takes thought. If you want an app that quietly records transactions with almost no decisions from you, this approach may feel like extra work rather than help.
Where setup can feel less simple
Connecting accounts can be convenient, but I would not treat a connection as a substitute for checking the budget. When an account is unavailable or a transaction has not appeared yet, the useful question is whether the available balance and the plan still make sense. For anyone who prefers not to connect financial accounts, a manual routine is also worth considering: enter activity yourself and reconcile it against the balances you can see. That takes attention, but it keeps the budgeting decisions in your hands.
I recommend choosing categories based on decisions you actually make. “Food” may be enough if you do not need to distinguish groceries from meals out; if those compete for the same limited amount, splitting them can make the trade-off visible. Too many tiny categories at the start create maintenance without necessarily improving decisions. A short, useful plan is easier to keep current than a detailed one you abandon.
Make the routine fit ordinary days
A realistic use case is payday followed by a week of competing needs. I would first cover bills due before the next pay, then set aside money for essentials such as food and transport, and only then decide what can go toward a future purchase. If an unexpected expense appears, the plan gives you a place to make a deliberate adjustment: move money from a less urgent purpose instead of treating the overspend as invisible. That is a practical strength, but it does not make a tight budget painless; it helps show the choice clearly.
One helpful habit is to check the plan before spending in a category that is close to its limit, rather than waiting until the end of the month to review a report. Another is to revisit categories when life changes: a new bill, a different commute, or a seasonal expense can make last month’s plan misleading. These small reviews are more valuable than chasing perfect records. The app works best when the budget reflects current priorities, not an ideal version of your finances.
Checks that help when something looks wrong
If a balance seems off, I would check the account balance, recent activity, and the category affected before changing several parts of the budget at once. A delayed or missing transaction can make the plan look different from reality, while an incorrect entry can distort what remains available. Correcting one issue at a time makes it easier to see what changed. If you track activity manually, a regular comparison with your account records is especially useful.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
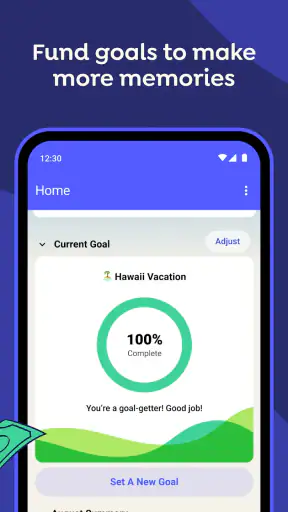
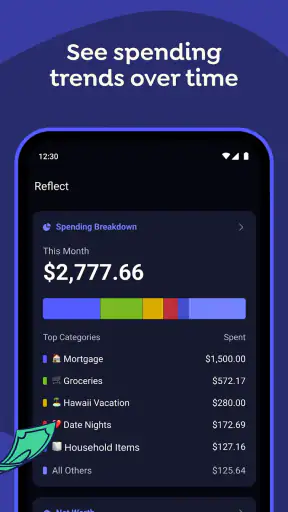
Goals can help give a longer-term purpose to money, but they work best when the amount and timing are grounded in your circumstances. A target for a laptop or a trip can make saving feel concrete; it should not take priority over a bill that is due sooner simply because the goal looks motivating. I would use progress views as a prompt to review the plan, not as a scorecard. Reports can help you notice patterns, but they are most useful when they lead to a decision you can act on.
Who benefits most from this style
This approach suits people who want to be more intentional with money and are willing to check in regularly. It can be especially useful if your income arrives on a schedule but several expenses fall at different times, or if you are trying to balance current bills with savings goals. Someone sharing household decisions may also find the act of agreeing on priorities more useful than simply looking at a list of past purchases.
It may be the wrong fit if you want a passive dashboard, dislike assigning money before spending, or know that frequent upkeep will become a burden. A simple spreadsheet or a lighter spending tracker may be better if your needs are limited to recording purchases and checking totals. Compared with those alternatives, YNAB asks for more active participation in exchange for a more forward-looking plan. The trade-off is central, not a minor setting you can ignore.
Getting Started with YNAB
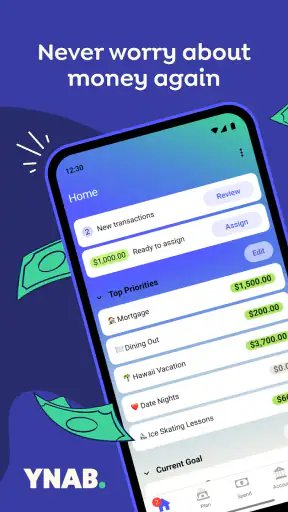
Diving into YNAB is surprisingly straightforward. The app greets you with a user-friendly interface that doesn’t overwhelm. Trust me, I’ve tried budgeting apps before that felt like deciphering a financial cryptic puzzle. But with YNAB, setting up my bank accounts and categorizing my expenses was a breeze. It’s like the app knows we’re not all financial gurus and meets us right where we are.
Features That Stand Out
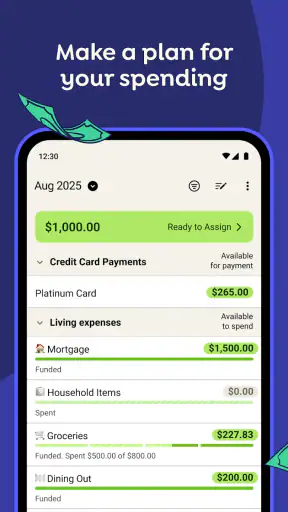
What really impressed me was the app's philosophy of “giving every dollar a job.” It’s a proactive approach to budgeting, ensuring that every penny is accounted for before it’s spent. This isn’t just about tracking what you’ve already spent; it’s about planning ahead. And the real-time syncing across devices? Absolute game changer. Whether I’m on my phone or laptop, my budget is always up-to-date.
Another cool feature is the goal tracking. I set a couple of savings goals — a new laptop and a trip to Italy (a girl can dream, right?) — and YNAB helps me stay on track with progress updates. It’s like having a friendly nudge reminding you to save, without the nagging. Plus, the reports and visual graphs are super satisfying for those of us who like to see where our money goes at a glance.
Learning Curve & Community
Now, I won’t lie, there’s a bit of a learning curve. But YNAB offers a ton of free workshops and video tutorials. The app’s community is also pretty great. I found myself diving into forums and connecting with other users who share budgeting tips and success stories. It’s comforting to know you’re not alone in your financial journey.
In practice, I would give the learning process time rather than judging the app after the first setup session. Try a short list of categories, make the next spending decision inside the plan, and then adjust the plan when reality differs. That sequence teaches the method more naturally than trying to forecast every future expense at once. If you lose track for a few days, start with what is currently available and the next obligations; there is no need to reconstruct an elaborate ideal month before making the next useful choice.
The subscription is another decision to make before committing to a long-term routine. The app is free to install, while in-app purchases range from $14.99 to $109.00 per item. I would weigh that cost against how much value you personally get from active planning, not against an imagined promise that budgeting will automatically create spare money. If you only need a record of purchases, a free basic tracker or spreadsheet may be enough. If the structure helps you make trade-offs you were previously avoiding, paying for a budgeting system may feel more worthwhile.
When the problem may be outside the app
A budget can look impossible when the underlying issue is that essential costs exceed income. No category layout can solve that by itself. In that situation, the useful role of a plan is to make the shortfall and the timing of obligations easier to see, so you can decide what needs attention first. I would avoid treating a missed target as a personal failure; revise the plan to match the money available and focus on the next concrete decision.
Likewise, if a number differs between the app and an account, changing categories repeatedly may only hide the source of the mismatch. Check whether the transaction is present, whether the amount is right, and whether you are comparing the same balance and time period. If the issue is an account connection or a device problem, basic checks such as confirming that the app is current and that the device has a working connection are sensible first steps. The current version is 25.37.2, and the minimum operating system is 10. Those details matter when deciding whether an older device is suitable.
For a first-time budget, I would also avoid making the categories too aspirational. If spending on eating out is a real part of your routine, leaving it out does not make it disappear; it only makes the plan less honest. Start with amounts you can explain, then adjust them as you learn. A useful budget is not the one that looks most disciplined on screen; it is the one that helps you choose what to do when two reasonable priorities compete.
How it compares with familiar alternatives
Many finance apps are designed to summarize spending, show account activity, or provide a quick overview. Those can be a better match if your main question is “Where did my money go?” YNAB is more suitable when you want to decide what available money should do next. A spreadsheet can also support that kind of planning, with more freedom over layout and no built-in method to learn, but it requires you to maintain the structure yourself. The difference is less about which option is universally best and more about whether you want guidance and an ongoing budgeting habit.
Its audience is broad: the app has an Everyone content rating, an average rating of 4.6 from around 23,000 ratings, about 4,500 reviews, and more than one million installs. Those figures suggest plenty of people have tried it, but they cannot tell you whether its hands-on style will fit your household. I would use the method itself as the deciding factor. If assigning money to purposes sounds useful rather than restrictive, there is a good reason to try it; if you resent that step, a simpler tracker is probably the better choice.
Final Thoughts
Is YNAB perfect? Not quite. It does come with a subscription fee, which might be a turn-off for some. But, let’s be real, if it helps you save more than you spend, it’s worth every penny. I’ve found that YNAB is more than just a budgeting tool; it’s a mindset shift. It encourages you to think differently about your money, and for that, I’m sold.
So, if you’re looking to take control of your finances and want an app that does more than just track spending, YNAB could be the answer. Give it a shot and see if it changes your financial game like it did for me!
My practical verdict is that this is a strong choice for someone ready to participate in budgeting, not just inspect it. I would begin with a manageable plan, check it before meaningful spending, and treat every adjustment as information about priorities rather than evidence of failure. If you want a more passive view of your finances, choose a lighter alternative. If you want a deliberate routine that connects today’s available money to upcoming needs, YNAB is worth considering.
Frequently Asked Questions
01What is YNAB and how does it work?
YNAB, short for You Need a Budget, is a budgeting app designed to help users take control of their finances by assigning every dollar a job. It works on the principle of proactive budgeting, where you plan your spending ahead of time. Users can track their income and expenses, set financial goals, and adjust their budget as circumstances change.
02Is YNAB suitable for beginners in budgeting?
Yes, YNAB is very beginner-friendly. It offers a comprehensive set of tutorials and educational resources to help new users understand the budgeting process. The app’s user interface is intuitive, making it easy to navigate. Additionally, YNAB provides workshops and a supportive community to assist users in mastering their personal finances.
03What platforms can I use YNAB on?
YNAB is available on multiple platforms, including Android and iOS for mobile devices, as well as web browsers for desktop access. This cross-platform availability ensures that you can manage your budget on-the-go or from the comfort of your home, synchronizing seamlessly across all your devices.
04Does YNAB require a subscription, and is there a free trial available?
YNAB operates on a subscription model, offering monthly and annual payment options. While it is a paid service, new users can take advantage of a 34-day free trial to explore the app’s features and determine if it suits their budgeting needs before committing to a subscription.
05How secure is my financial information with YNAB?
YNAB takes security very seriously, employing bank-grade encryption to protect your data. The app uses two-factor authentication and does not store your banking credentials. User privacy is prioritized, ensuring that your financial information remains secure while you focus on managing your budget.


